


There is a big difference between being told that something costs ₦400,000 and being told that you can pay ₦40,000 every month for 10 months.
The total cost is the same, but the second option feels easier to handle. That is one of the reasons Buy Now, Pay Later (BNPL) has become an attractive way to pay for products and services. Instead of paying the full amount upfront, customers can spread the cost over a period of time.
There is nothing wrong with paying in instalments. The problem is that smaller payments can sometimes make us lose sight of how much we are actually spending.
Research from the Consumer Financial Protection Bureau found that BNPL users tend to make more purchases and are more likely to have multiple BNPL loans at the same time.
That is where things can get complicated.
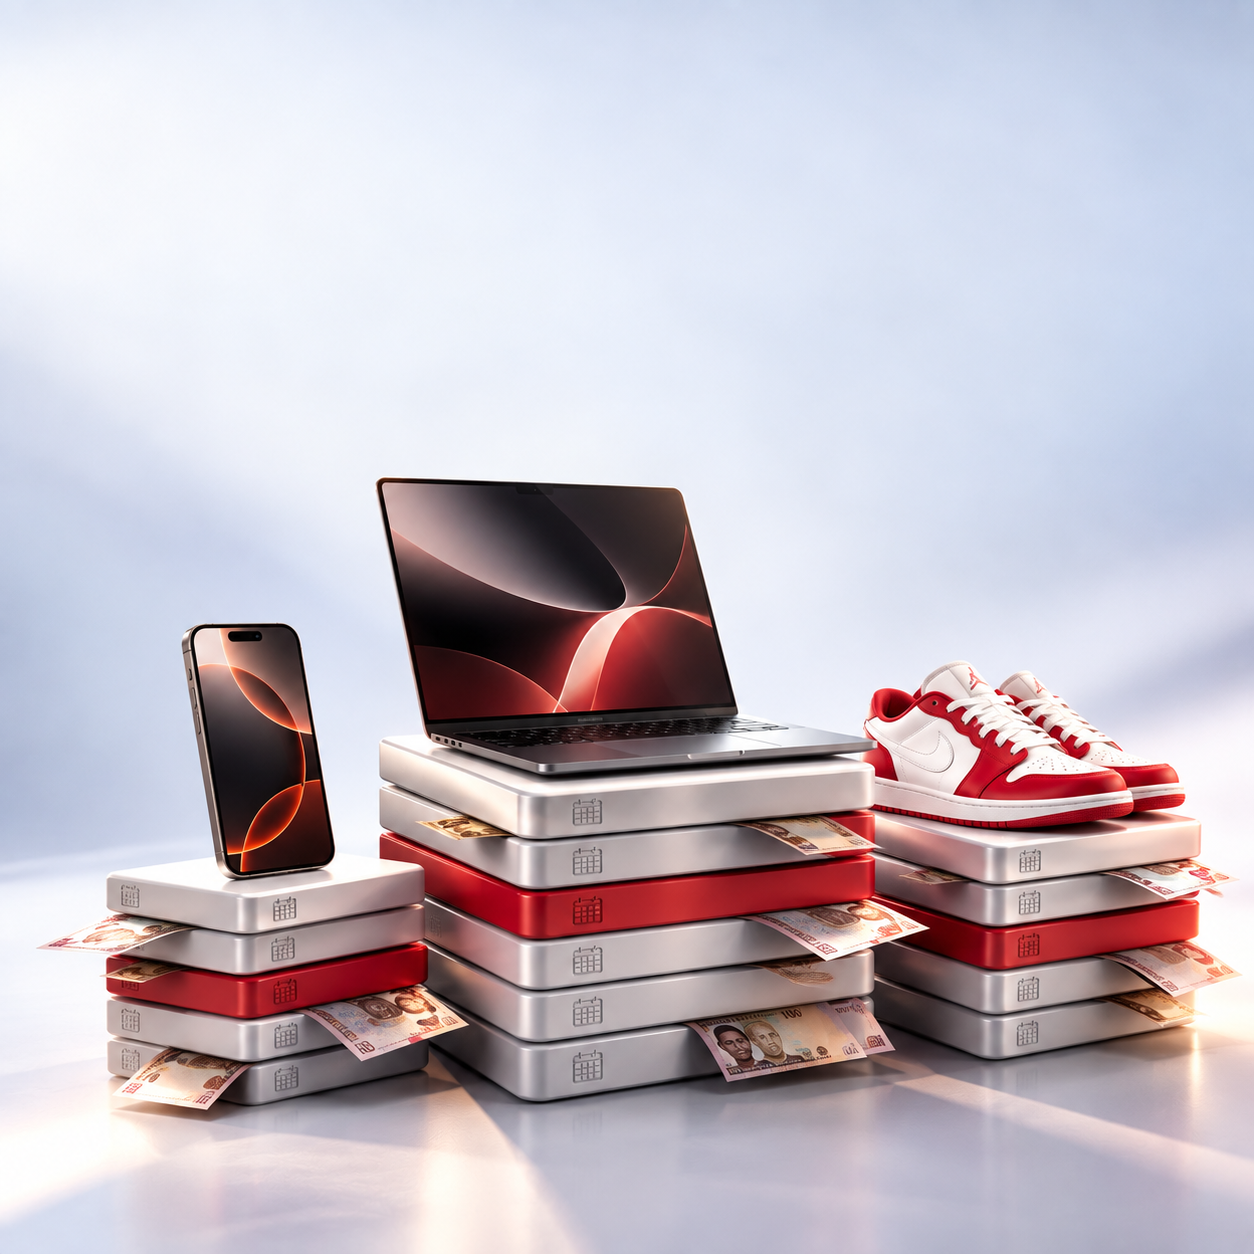
You might be comfortable paying ₦40,000 a month for a phone. Then you need a laptop and take another plan that costs ₦60,000 a month. A few weeks later, you decide to replace your headphones and add another ₦15,000.
Individually, none of these payments may seem like a major burden. Together, you are now committed to ₦115,000 every month.
This is why looking only at the monthly payment can be misleading. Before taking on an instalment plan, it is worth considering the total amount you will eventually pay and how it fits with everything else you already have to pay for.
There is also the question of what the smaller payment does to our purchasing decisions.
Something you might not have bought for ₦500,000 can suddenly feel possible when you are told it will cost ₦50,000 a month. The same applies to smaller purchases. You may not have planned to buy another pair of sneakers, but ₦15,000 a month can make the decision feel easier.
The question quietly changes from “Do I need this?” to “Can I afford the monthly payment?”
But those are not the same question.
Being able to make an instalment does not necessarily mean you can afford the purchase. Your income, existing expenses, other loans, interest and fees, the length of the repayment period and unexpected expenses all matter.
It is also worth looking at how many instalment payments you already have. If you are taking on a new payment before finishing an old one, your future income is already being committed to several purchases.
BNPL is not automatically a bad financial decision. It can be useful when the repayment fits comfortably within your budget and you understand the terms. The issue is when the instalment option makes something affordable in your mind when it really is not affordable for your overall finances.
So before choosing “Buy Now, Pay Later”, look beyond the monthly amount. Check the total cost, the fees, your existing commitments and whether you actually need the purchase.
A smaller payment may be easier to manage, but it does not make the purchase cheaper.