



If you have heard that the CBN just cut interest rates and wondered what that actually changes for you, the short answer is: potentially quite a bit, but probably not in the way the headline makes it sound.
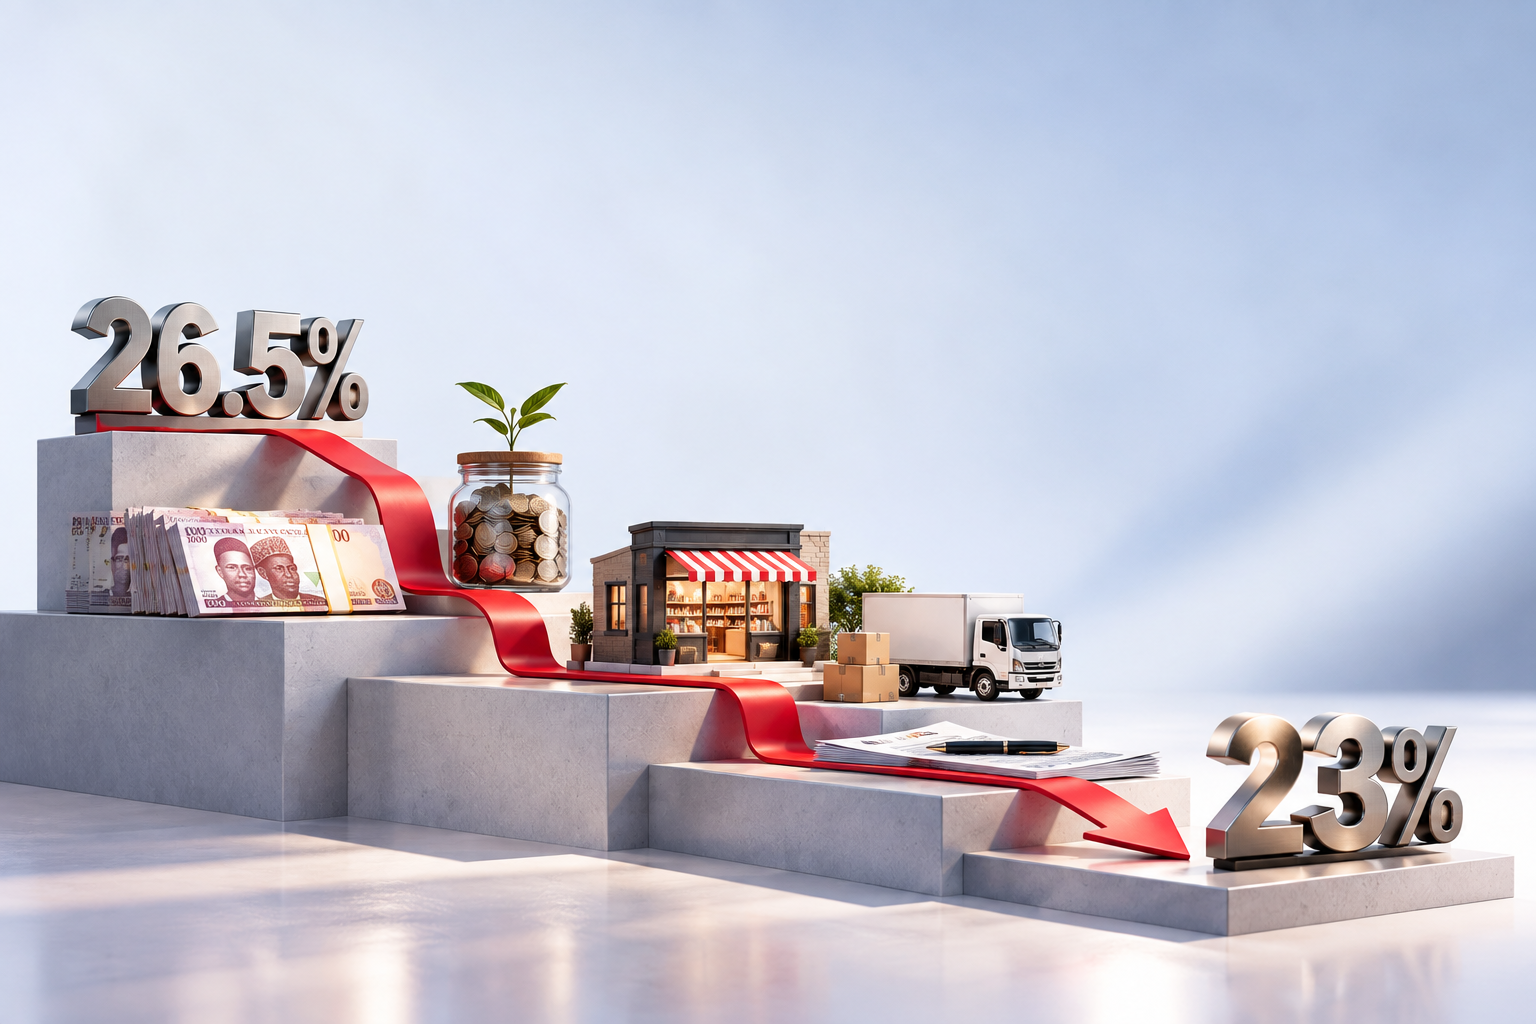
On September 22, 2026, the Central Bank of Nigeria (CBN) reduced its Monetary Policy Rate (MPR) from 26.5% to 23%, cutting 350 basis points. It is the largest single reduction in the benchmark rate since 2006.
That is a significant shift. But before getting into what it means for your money, it helps to understand what exactly has changed.
So, What Exactly Did the CBN Change?
The MPR is the benchmark rate the CBN uses to influence monetary conditions across the economy. It helps shape the direction of other interest rates, including the rates at which banks lend and the returns available across some savings and investment products.
It is not, however, the rate attached to your personal loan or savings account.
That is an important distinction. If the MPR falls by 3.5 percentage points, your loan does not automatically become 3.5 percentage points cheaper. Banks still consider their own funding costs, the type and duration of the facility, the borrower’s risk profile and other market conditions when setting lending rates.
So the 23% figure is better understood as a signal about where the cost of money is heading than as a rate you can simply apply to your own finances.
If you are planning to borrow, this is where the rate cut could become interesting.
For a business owner who has been putting off buying equipment, increasing inventory or opening another location because the financing cost was too high, a lower-rate environment could eventually make borrowing more affordable.
The same applies to individuals considering credit for major purchases or other financial needs, but the word to watch here is eventually. The CBN changing its benchmark rate does not mean every lender changes its rates immediately. How much of the reduction reaches borrowers, and how quickly, depends on how the change moves through the financial system.
For anyone with an existing loan, the terms of that loan matter too. A new MPR does not automatically change an agreement that is already in place.
Now if your money is earning interest, that is another side to a falling-rate environment.
If you have money in an interest-bearing savings or investment product, changes in market rates can affect the returns available on those products, particularly when they are repriced or renewed.
This is why interest-rate decisions matter to both borrowers and savers, although for very different reasons. A borrower is interested in what it costs to access money. A saver or investor is interested in what that money can earn.
The rate environment can influence both sides of that equation.
What It Does Not Tell You About Prices
This is probably where the biggest misunderstanding comes in.
A lower MPR does not mean your grocery bill is about to fall. It does not determine rent, fuel prices or transport fares. Those prices are influenced by a wider mix of factors, including inflation, exchange rates, energy costs, supply and production expenses.
The rate cut can, however, influence the cost of financing businesses that produce and move those goods. If credit becomes more affordable, businesses may find it easier to invest, expand production or finance working capital.
Whether that eventually translates into broader economic benefits is a different question, and one that will take time to answer.
So, What Should You Watch Now?
The announcement itself is only the beginning.
The more useful things to watch are the rates financial institutions offer on new loans, what happens to returns on savings and investment products, and whether businesses begin to find financing more accessible.
That is where the 23% will become real for most people.
Interest rates may be decided in a CBN meeting, but their impact eventually shows up in ordinary financial decisions: whether a business takes on new equipment, whether someone takes a loan, where an investor puts their money and what return a saver can expect.
The MPR has changed.
Now we wait to see how much of that change makes its way into the money decisions Nigerians make every day.