


There is always that one thing you want to do.
The business needs a bigger freezer. Your car has decided that every trip must come with a prayer point. You have found a house you like, but the money sitting in your account is not quite agreeing with the landlord’s expectations.
Or perhaps you are simply trying to get through a financially demanding month without scattering the plans you have been making for the past year.
The plans are there. The money is where the conversation gets interesting.
And in these times, when one unexpected expense can rearrange an entire budget, sometimes the distance between wanting to do something and actually doing it comes down to financing.
But before you borrow, there is one important question: what kind of loan actually fits what you need?
Every Problem Is Not Looking for the Same Loan
Imagine three people.
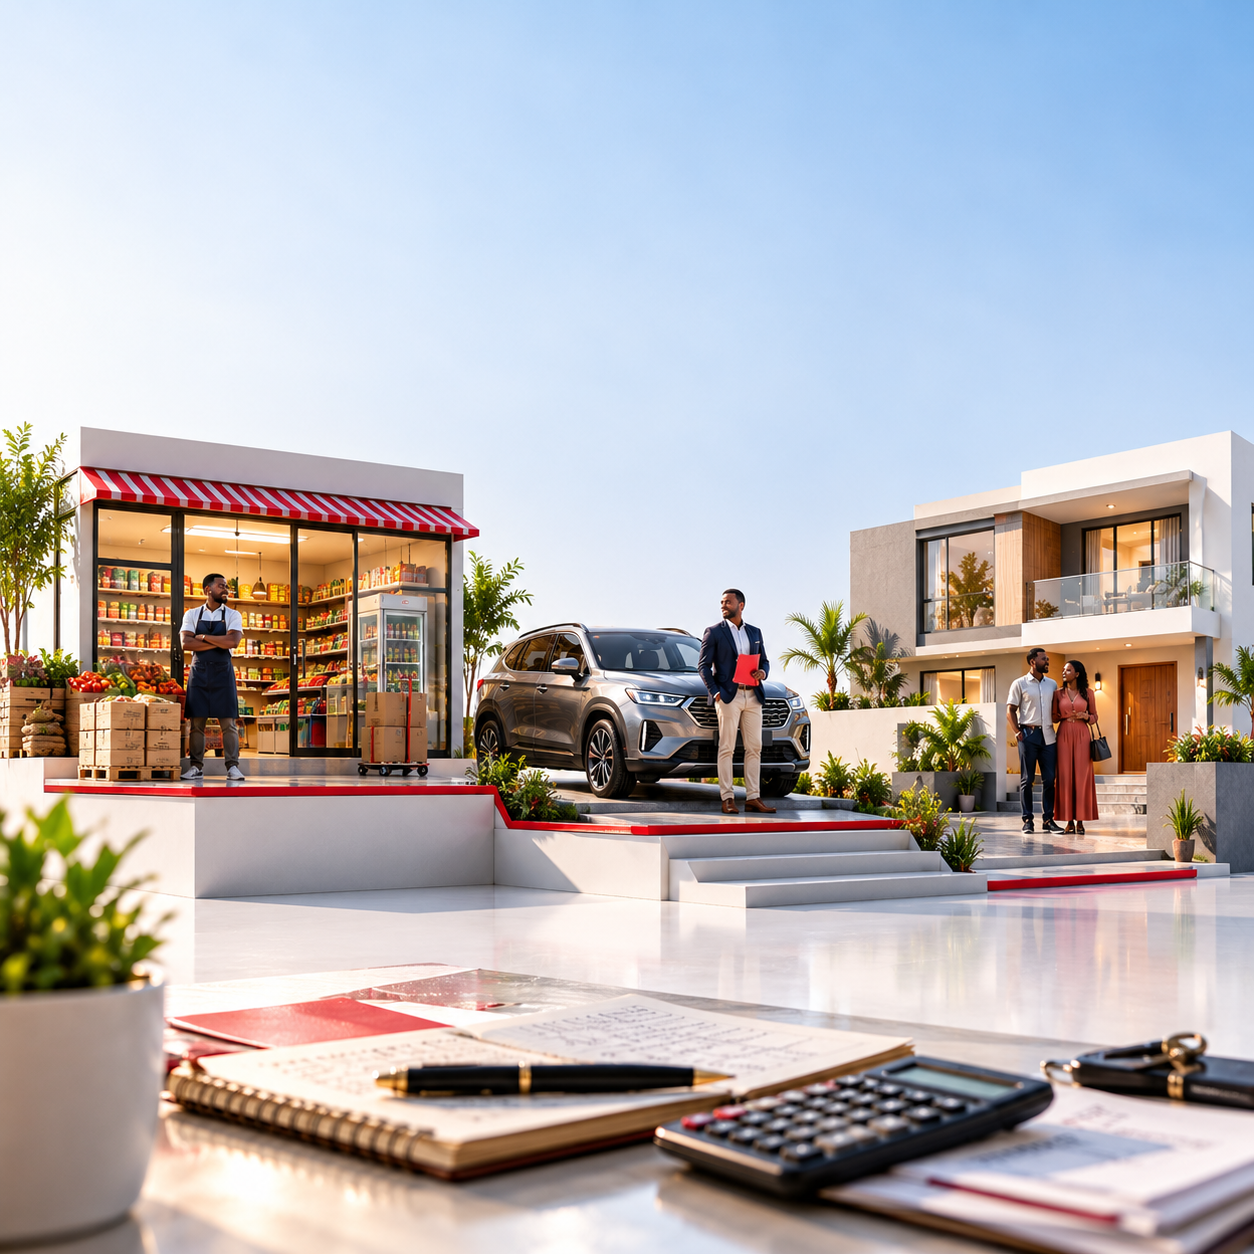
The first is a salary earner who wants to buy a car. The second runs a business and needs money to support its operations. The third is looking to buy a home.
All three need financing.
But giving them the same loan would be like prescribing paracetamol for every complaint because everybody has a headache at some point.
The purpose matters.
So does the amount, the repayment period, the cost of borrowing and, most importantly, whether the borrower can comfortably repay.
That is why Sterling offers different financing options for different needs.
When Your Salary Has Plans Beyond Payday
A regular salary can make certain things easier to plan for. It does not mean every major expense will politely wait until you have saved enough.
Sterling’s payroll lending options provide eligible salaried employees with access to personal loans. Depending on the employer category and applicable terms, Sterling offers facilities of up to ₦60 million.
For salary earners looking for digital lending options, Specta is another route. Specta Basic is available to eligible customers with regular income, with loan amounts typically ranging from ₦50,000 to ₦5 million. Eligibility, rates and other conditions apply.
Then there is Vehicle and Asset Finance for eligible salaried customers looking to acquire items such as cars, laptops, refrigerators and other appliances.
Instead of treating every purchase as a separate financial emergency, the idea is to understand which financing option fits the purchase and your ability to pay it back.
Because a new car is nice. A new car followed by months of repayment regret is a different experience entirely.
Your Business Needs More Than Encouragement
Every small business owner knows the difference between having customers and having enough cash to serve them.
Orders may be coming in, but the business still needs stock. A new opportunity may appear, but the equipment required to take it on costs money. Sometimes, the business is ready to grow, but the funds needed to support that growth are not available yet.
This is where business financing can enter the conversation.
Sterling’s Business Support Facility (BSF) is designed for eligible small and medium-sized enterprises. Sterling offers facilities of up to ₦20 million under the scheme, with amounts up to ₦5 million not requiring collateral. Larger amounts require tangible collateral, and eligibility criteria apply.
The scheme is not a free pass for every business with a good idea. Requirements include registration with the Corporate Affairs Commission and a minimum operating history of three years, alongside other business, banking and credit conditions.
That distinction matters.
Borrowing to support a business makes more sense when you understand what the money will do, how it could improve operations and where the repayments will come from.
A loan should support the business plan, not become the business plan.
Before You Collect, Let’s Talk About Repayment
There is a part of borrowing that deserves as much attention as the money arriving in your account.
The money leaving it.
Interest rates, fees, repayment periods and eligibility requirements all affect what a loan will eventually cost you. The amount you qualify for is not necessarily the amount you should borrow.
Before applying, consider:
- Purpose: What exactly will the money pay for?
- Affordability: Can you make the repayments without neglecting essential expenses?
- Total cost: What are the interest rate, applicable fees and other charges?
- Repayment period: Does the tenor fit your income or expected business cash flow?
- Risk: What happens if your income drops or the business has a difficult month?
Read the terms carefully and ask questions where anything is unclear.
The goal is not simply to access money. It is to access financing you understand and can manage.
Sterling’s loan offerings cover different needs, from payroll lending and digital loans to business financing, vehicle and asset finance, and home acquisition finance.
You can explore the available options and their requirements on the Sterling loan page.
Because big plans are good.
Growing a business is good. Buying a car is good. Owning a home is good.
But the real win is making the move without putting your financial future in a chokehold.